Latest full forecast
╭────────────────────────────────────────────────────── SPXLcast ──────────────────────────────────────────────────────╮
│ SPXL 270.35 close 2026-10-30 | S&P 500 7,580 | VIX 19.4 | 3m bill 4.18% | 10y 5.05% │
╰─────────────────────────────── prices fetched 2026-10-30 20:40 UTC | run 21:40 UTC ────────────────────────────────╯
╭───────────────────────────────────────────────────── Assessment ─────────────────────────────────────────────────────╮
│ Leverage cost normal │
│ The S&P 500 has to return 7.5% a year on average, dividends included, for SPXL just to break even │
│ over the long run. │
│ That is higher than in 62% of the months from 1990 to 2026 (low = the cheapest third of those months, │
│ high = the costliest third). │
│ Compared with 3 times the S&P 500's return, SPXL gives up about 18.0% a year: borrowing 9.9% (it │
│ borrows 2 times its own value and pays the 3-month Treasury bill rate, 4.18%, plus 0.75% on it), fees │
│ 0.84%, and volatility drag 7.3% (SPXL resets to 3x every day, which loses money when the market │
│ zigzags: the bigger the swings, the bigger the loss. The model expects the S&P 500 to swing about 16% │
│ a year). │
│ The S&P 500 has to make up only about a third of that (6.0%), plus a little for its own swings: hence │
│ the 7.5%. │
│ For comparison: the model's long-run S&P 500 estimate is +6.3% a year. It is an average over many │
│ years, not a forecast for the coming months, and since 1990 it has run below what the S&P 500 │
│ actually returned. │
│ │
│ Drawdown risk normal │
│ 29% chance SPXL closes at or below 216.28, a fall of 20% or more from 270.35, on some day in the next │
│ 3 months (even if it recovers afterwards). │
│ That is higher than in 59% of the months from 1990 to 2026 (low = the calmest third of those months, │
│ elevated = the riskiest third). │
│ In the backtest's 143 months at this level from 1990 to 2026, the model would have said 25% on │
│ average, and such a fall followed 22% of the time. Before 2009 these use a 3x fund rebuilt from the │
│ S&P 500, as SPXL did not exist yet; and neighbouring months share most of their 3 months, so there │
│ are fewer separate cases than months. │
│ │
│ 3-month range In 3 months SPXL ends between 173.68 and 379.23 in 90% of the model's simulations (5% end lower, 5% │
│ higher); the typical (middle) outcome is 275.10. In the 1990-2026 backtest, ranges like this held │
│ about 9 times in 10. │
│ │
│ This is not a buy or sell signal. In the 1990-2026 backtest, months at high leverage cost or elevated │
│ drawdown risk were not followed by lower returns on average (elevated risk did bring more 20% falls), │
│ and the months the old buy/hold/sell rating marked as a buy did no better than the rest, which is why │
│ it is no longer shown. │
╰──────────────────────────────────────────────────────────────────────────────────────────────────────────────────────╯
SPXL price distribution (spot 270.35)
Horizon Mean P5 P25 Median P75 P95 P(up) P(>bill) P(>S&P) P(dd 20%)
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
1W 271 241 261 271 281 299 53% 52% 52% 1%
2W 271 228 257 272 286 311 53% 53% 52% 4%
1M 272 210 250 273 295 332 54% 52% 51% 10%
3M 276 174 235 275 315 379 53% 51% 49% 29%
6M 281 145 221 277 335 431 53% 50% 48% 43%
1Y 292 108 195 275 368 537 51% 48% 44% 59%
P(up): ends above spot. P(>bill): beats the T-bill. P(>S&P): beats the unlevered index. P(dd 20%): touches -20% from
spot at some point before the horizon.
Returns (SPXL vs. unlevered S&P 500 total return vs. T-bill)
Horizon SPXL median SPXL mean SPXL 5% worst S&P median T-bill
─────────────────────────────────────────────────────────────────────────
1W +0.4% +0.2% -11.0% +0.2% +0.1%
2W +0.7% +0.4% -15.7% +0.4% +0.2%
1M +1.1% +0.7% -22.4% +0.8% +0.3%
3M +1.8% +1.9% -35.8% +2.0% +1.0%
6M +2.3% +4.0% -46.2% +3.6% +2.1%
1Y +1.7% +8.1% -60.2% +6.5% +4.2%
Price 200.00 (-26.0% vs spot 270.35)
P(dips to level) = buy-limit P(rises to level) = sell-limit
Horizon Percentile of end price P(end above) fill fill
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
1W 0th 100% 0% already above
2W 1st 99% 1% already above
1M 3rd 97% 5% already above
3M 11th 89% 18% already above
6M 17th 83% 31% already above
1Y 26th 74% 49% already above
Price 250.00 (-7.5% vs spot 270.35)
P(dips to level) = buy-limit P(rises to level) = sell-limit
Horizon Percentile of end price P(end above) fill fill
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
1W 10th 90% 14% already above
2W 17th 83% 26% already above
1M 25th 75% 41% already above
3M 34th 66% 62% already above
6M 38th 62% 72% already above
1Y 42nd 58% 81% already above
Percentile = share of simulated end-of-horizon prices at or below the level (a low percentile means the level is a cheap
outcome). Fill probabilities use the whole simulated path: a buy-limit placed below spot fills if the price dips to it
at any point before the horizon.
Buy-limit ladder over the next 6M (chance the price dips to the level)
P(fill) Limit price vs spot Median end vs entry (if filled) P(profit if filled)
─────────────────────────────────────────────────────────────────────────────────────────
90% 267.14 -1.2% -0.3% 50%
75% 253.20 -6.3% -1.3% 48%
50% 225.92 -16.4% -2.1% 46%
25% 188.45 -30.3% -2.6% 45%
10% 151.19 -44.1% -3.9% 42%
The last two columns only count the paths on which the order actually fills, so they already reflect that a dip to the
level is bad news on average.
S&P 500 expected total return (annualised) - how it is built
Component Value Detail
─────────────────────────────────────────────────────────────────────────────────
Earnings-yield model +6.5% E/P 4.14% + inflation 2.35%
Dividend-growth model +6.3% div yield 0.99% + nominal EPS growth 5.35%
Base (50/50 blend) +6.4%
adj: hot_inflation -0.1% risk-regime penalty
CPI YoY 3.72% above 3.50%
Final index drift +6.3% clipped to [-10%, +20%]
News tilt (first 10 days) +0.0% Neutral (+0.00); kept small, not calibrated
Volatility (from the VIX term structure) and SPXL mechanics
Item Value Detail
──────────────────────────────────────────────────────────────────────────────────────────────────────────────────────
Index vol pillar 1M 16.4%
Index vol pillar 3M 15.8%
Index vol pillar 6M 15.2%
Index vol pillar 1Y 15.6%
Index vol to 6M 15.2% variance-consistent average
Daily shock shape t(4), skew 0.90 fat tails; skew < 1 means larger down moves than up moves
Leverage 3.00x stated 3x, checked against realised beta
Expense ratio 0.84%
Financing cost 9.86% (2x) x (3m bill + 0.75% all-in spread)
Volatility drag to 6M 6.9% L(L-1)/2 x sigma^2 at the 6M vol (emerges in the simulation); the
assessment's figure uses the 1-year vol
Break-even index return 7.5% the leverage-cost hurdle: average index return at which SPXL's long-run
(log) growth is zero, at the 1-year vol; the simulated 1-year median
sits higher, because volatility comes in bursts
Realised beta / R2 2.97 / 0.999 504 days, 4 dislocation days excluded; tracking noise 0.08%/day
pillars after VRP haircuts of 3/5/7 pts: 21d 16.4%, 63d 15.8%, 126d
15.2%, 252d 15.6%
realised 3m vol of SPY: 10.4% (diagnostic only)
expense ratio 0.84% (Yahoo info.netExpenseRatio)
calibrated on 504 days (4 dislocation days excluded): beta 2.970, R2
0.999, tracking noise 0.079%/day, empirical drag +10.2%/yr (noisy)
financing 2x (4.18% + 0.75% all-in spread) = 9.86%/yr
Influencers - current levels
Ticker Description Last 1D 1M 3M 1Y
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
SPXL Direxion Daily S&P 500 Bull 3X 270.35 -5.4% -4.4% -3.2% +18.3%
SPY SPDR S&P 500 ETF (total-return proxy) 755.72 -1.8% -1.1% -0.0% +11.1%
^GSPC S&P 500 index 7,580.07 -1.8% -1.1% -0.3% +10.0%
^VIX VIX (30-day implied vol, %) 19.42 +2.22 +3.03 +3.56 +2.50
^VIX3M VIX 3-month (%) 20.78 +1.41 +2.20 +1.85 +0.95
^VIX6M VIX 6-month (%) 22.20 +0.96 +1.68 +1.00 +0.18
^VVIX VVIX (vol of vol) 106.43 +8.42 +14.42 +15.62 +2.86
^SKEW CBOE SKEW (tail-risk pricing) 151.03 +2.29 +9.11 +9.80 +10.66
^IRX 13-week T-bill, discount basis (%) 3.97 -0.02 -0.01 +0.27 +0.24
2YY=F 2-year yield future, CBOT front month (%) 4.75 +0.00 -0.14 +0.46 +1.31
^FVX 5-year Treasury yield (%) 4.72 -0.08 -0.28 +0.32 +1.02
^TNX 10-year Treasury yield (%) 4.93 -0.06 -0.31 +0.24 +0.87
^TYX 30-year Treasury yield (%) 5.31 -0.02 -0.29 +0.08 +0.71
DX-Y.NYB US Dollar Index 101.89 -0.1% -0.2% +1.9% +2.7%
HYG High-yield corporate bond ETF 77.43 -0.2% +0.7% -1.4% +1.4%
LQD Investment-grade corporate bond ETF 104.27 +0.0% +2.2% -0.9% -2.7%
TLT 20y+ Treasury ETF 81.84 +0.4% +5.3% +0.4% -6.0%
CL=F WTI crude ($/bbl) 103.13 +1.1% +11.0% +28.4% +70.5%
GC=F Gold ($/oz) 3,889.20 -3.5% -7.5% -4.9% -2.8%
Yield and volatility rows show changes in points; price rows show % changes. Changes are aligned to the trading
calendar; n/a means the series has a gap there.
S&P 500 valuation and macro backdrop
Metric Value Source
────────────────────────────────────────────────────────────────────────────────
Trailing P/E 24.2 Yahoo:SPY.info.trailingPE
Earnings yield (E/P) 4.14% Yahoo:SPY.info.trailingPE
Dividend yield 0.99% Yahoo:SPY.info.yield
Nominal EPS growth assumed 5.35% real 3.0% + inflation 2.35%
Price/Book 5.25 Yahoo funds_data
Price/Sales 3.64 Yahoo funds_data
3m T-bill (bond-equivalent) 4.18% FRED:DGS3MO
2y yield 4.67% FRED:DGS2
10y Treasury 5.05% FRED:DGS10
30y Treasury 5.31% Yahoo:^TYX
Curve 10y-3m +0.87%
10y breakeven inflation 2.35% FRED:T10YIE
Real 10y yield +2.67% FRED:DFII10
E/P minus real 10y +1.47% context only
HY credit spread (OAS) 3.14% FRED:BAMLH0A0HYM2
CPI YoY 3.72% FRED:CPIAUCSL
Unemployment 4.2% FRED:UNRATE
VIX / 3M / 6M 19.4 / 20.8 / 22.2 Yahoo
VVIX / SKEW 106.4 / 151.0 Yahoo
Top S&P 500 constituents (weight, valuation, 1M move, news tone)
Symbol Name Weight Trailing P/E Forward P/E 1M News
───────────────────────────────────────────────────────────────────────────────────────────
NVDA NVIDIA Corp 8.4% 26.1 13.0 -11.4% n/a
AAPL Apple Inc 7.4% 39.6 36.1 +4.3% n/a
MSFT Microsoft Corp 5.8% 27.0 21.5 +1.8% n/a
AMZN Amazon.com Inc 3.7% 19.1 22.7 -3.2% n/a
GOOGL Alphabet Inc Class A 3.1% 14.7 18.6 -17.3% n/a
AVGO Broadcom Inc 2.5% 42.3 17.0 -5.1% n/a
GOOG Alphabet Inc Class C 2.5% 14.6 18.5 -16.9% n/a
META Meta Platforms Inc Class A 2.4% 21.0 17.3 -15.3% n/a
MU Micron Technology Inc 1.8% 12.1 4.3 -19.4% n/a
TSLA Tesla Inc 1.5% 430.9 181.9 +12.9% n/a
News tone is per company; share classes (e.g. GOOG/GOOGL) are merged into one.
What moves SPXL: daily OLS betas over the last year
Driver Shock SPXL move R2 Days
──────────────────────────────────────────────────────────
SPY total return +1% +3.00% 1.00 252
10y Treasury yield +1pp -15.27% 0.07 252
3m T-bill yield +1pp +1.59% 0.00 252
VIX +1pt -1.35% 0.68 252
US Dollar Index +1% -2.35% 0.10 252
High-yield bonds (HYG) +1% +7.47% 0.56 252
Long Treasuries (TLT) +1% +1.11% 0.08 252
WTI crude +1% -0.27% 0.15 252
Gold +1% +0.45% 0.11 252
Read: a +2.9% move for a +1% shock to SPY means SPXL moves about 2.9% per 1% SPY move on the same day. Yield shocks are
+1 percentage point, VIX +1 point. Descriptive statistics, not a trading signal.
╭─────────────────────────────────────────────────── News sentiment ───────────────────────────────────────────────────╮
│ Neutral score +0.00 from 0 unique recent stories (0 fetched); near-term drift tilt +0.0%/yr │
╰──────────────────────────────────────────────────────────────────────────────────────────────────────────────────────╯
no recent articles
note: No news returned by Yahoo; sentiment set to neutral
appended to /data/logs/forecast_log.csv
archived /data/archive/runs/2026-10-30/214021Z.json.gz (0 new stories)
wrote /data/output/forecast.json
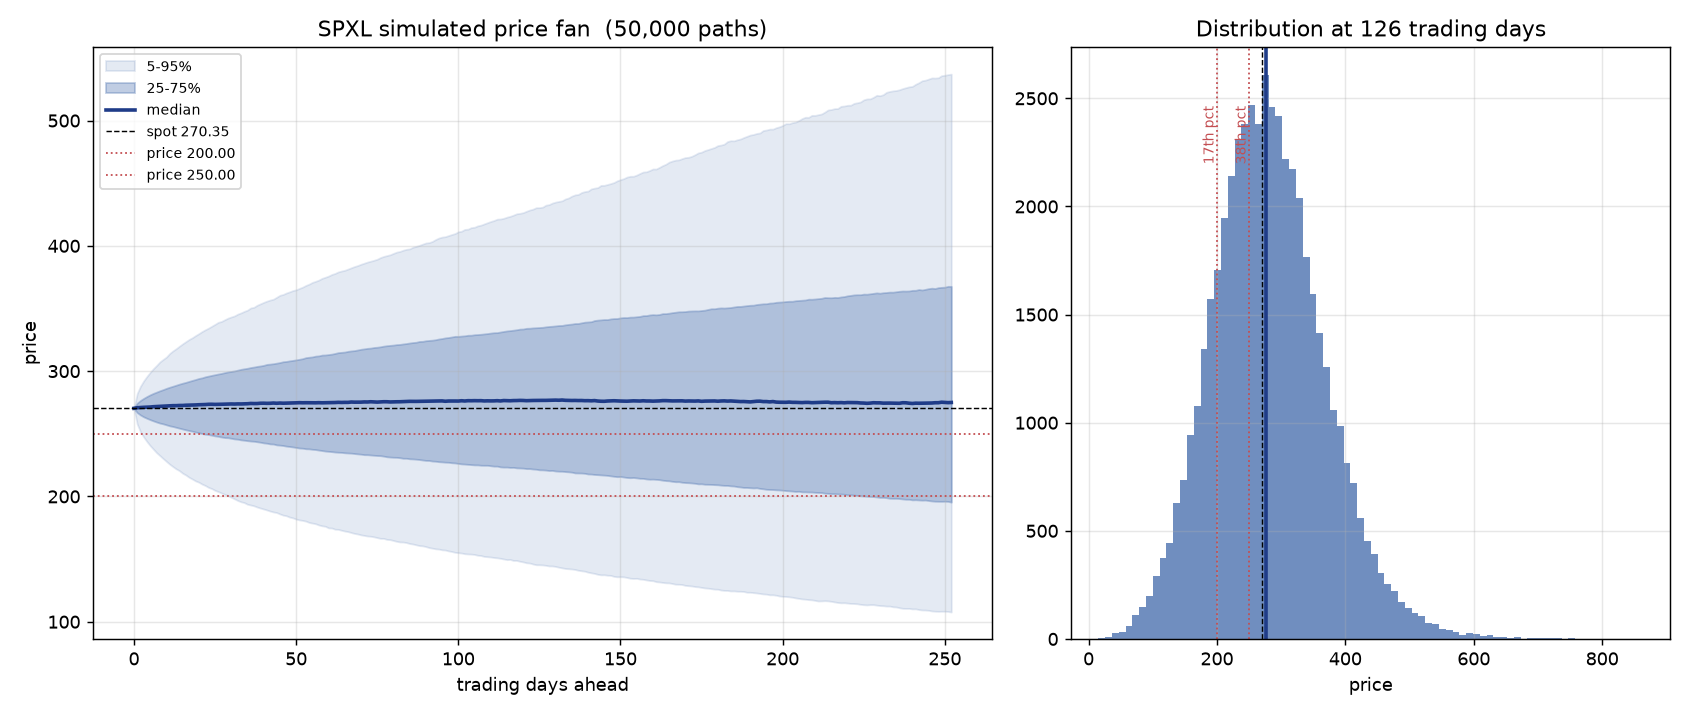
wrote /data/output/fan.png
Fan chart
Track record
╭──────────────────────────────────────────────────── Track record ────────────────────────────────────────────────────╮
│ 32 logged forecast dates  2026-09-16 to 2026-10-30   |   27 scoreable so far   |   /data/logs/forecast_log.csv   |   │
│ model 0.2.0 (7 rows), 0.3.0 (25 rows)                                                                                │
╰──────────────────────────────────────────────────────────────────────────────────────────────────────────────────────╯
note: rows from 2 model versions are pooled (0.2.0, 0.3.0); use --model-version to score one
Calibration: where realised prices fell in the forecast distribution (targets: mean PIT 0.50, 5-95 band 90%, 25-75 band
                                           50%, tails 5% each) [90% interval]

                                                                            Below 5 /          P(dd20)         P(up20)
  Horizon    n   Indep.         Mean PIT          In 5-95   In 25-75         above 95        pred/real       pred/real
 ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
       1W   20      4.8      0.47 [0.22,       100% [64%,        50%          0% / 0%            1%/0%           0%/0%
                                   0.71]            100%]
       2W   15      2.4       0.38 [n/a]       100% [n/a]        53%          0% / 0%            2%/0%           1%/0%
       1M   11      1.5       0.43 [n/a]       100% [n/a]       100%          0% / 0%            5%/0%           5%/0%

 Accuracy: CRPS of the log return (lower = better) against a naive lognormal at the raw VIX with a T-bill drift; skill
                                     above zero = the model beat it [90% interval]

  Horizon    n   Real mean ret   Pred median ret   CRPS model   CRPS naive                 Skill             Scored on
 ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
       1W   20           -0.1%             +0.3%       0.0197       0.0222        +11.3% [-4.8%,    20 fine / 0 coarse
                                                                                         +27.4%]                  grid
       2W   15           -1.6%             +0.6%       0.0263       0.0286           +8.2% [n/a]    15 fine / 0 coarse
                                                                                                                  grid
       1M   11           -0.6%             +1.1%       0.0277       0.0342          +18.8% [n/a]     4 fine / 7 coarse
                                                                                                                  grid

PIT = where the realised price fell in the predicted distribution (0 = below everything, 1 = above everything). A mean
far from 0.5 is bias; band coverage far from target is mis-sized dispersion. Indep. = how many independent outcomes the
rows amount to: forecasts a day apart share most of their window, so a year of daily 1-month forecasts holds about 12.
Intervals are on that many observations and appear once there are 3; until then the numbers are anecdotes, not evidence.
Fine = the run's 103-point grid from the archive; coarse = the 9 logged quantiles.
News score vs next-10-session SPXL return: correlation -0.19 over 22 dates. A value near zero means the news tilt has no
predictive content and can stay informational.